
By Tolu Ogunlesi
The new payments system quietly integrating a continent, unleashing business innovation, and empowering central banks with transaction data & trading insights.
Open your Nigerian banking app and chances are that you’ll see a PAPSS feature. It’s a platform that allows you to send Naira to any bank account at any participating African bank, anywhere on the continent, and the recipient receives the money in their own currency – Kwacha, Cedi, Egyptian Pound, CFA Franc. Transfer completed in an average of 7 seconds, for a fee 90–95 per cent lower than the previous norm.
For companies, PAPSS has a feature (an African currency marketplace) that allows a multinational (an airline, a brewer, an insurer) to easily transfer net profits from one African country to another. Back when the US dollar and the euro held a monopoly as the means of currency repatriation for companies operating in Africa, it was quite common to have profits stuck in various African countries owing to FX shortages. Now those funds can cross African borders more easily, reducing the pressure on global headquarters.
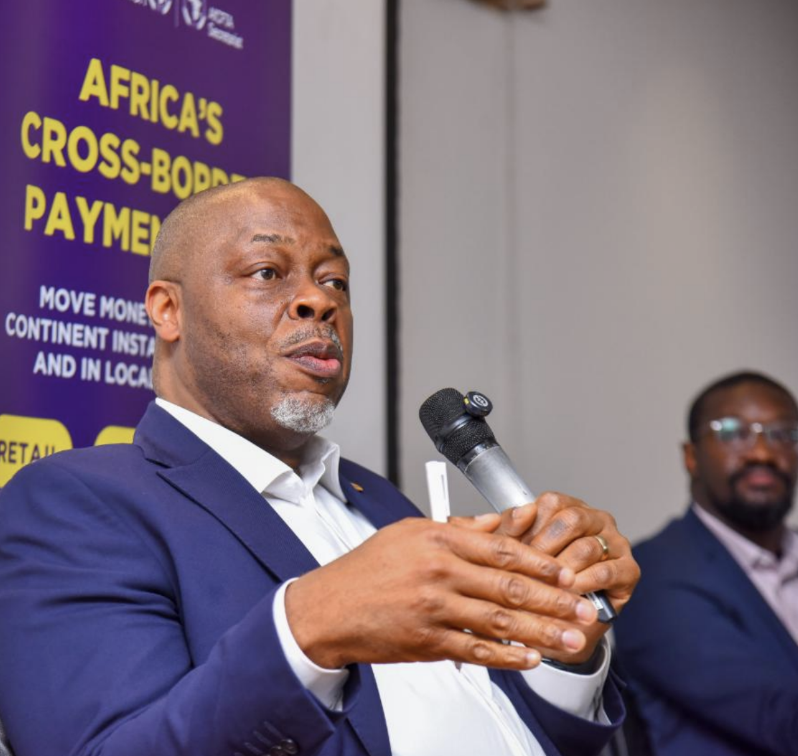
The ultimate goal of PAPSS is to, in the words of PAPSS chief executive officer Mike Ogbalu III, addressing editors and journalists in Lagos in early September, “create value for Africans,” through “a journey of the willing, not just about what PAPSS can do alone.”
Here’s what that value might look like: “We are creating PAPSS for [fintechs] to be able to address Africa’s 1.4 billion [fragmented] people. We can give you a single API that gives you [access to] the rest of Africa,” Ogbalu says.
“We’re hoping PAPSS will spark a fintech revolution across all of Africa, and that the shoemaker in Aba [Nigeria] is able to see the whole of Africa as his market.”
For Central Banks, PAPSS is fast becoming a reliable window into Africa’s widespread informal trade. “We are seeing a lot of informal trade transactions, and the Central Banks are now able to see those transactions today, unlike before when payments were done informally, by cash.”
Fascinating trading patterns: Nigeria–Rwanda, Nigerian churches
Four years after launch, PAPSS is throwing up really interesting patterns, scenarios and data points. Ogbalu: “We’ve seen heavy transactions between Nigeria and Ghana, and most interestingly now between Nigeria and Rwanda – almost even exceeding Nigeria and Ghana.”
There’s also, he says, a significant volume of transactions between Nigeria and Kenya.
And of course between Nigeria and its neighbours: Benin, Niger and Cameroon. “[Nigerian] banks were telling us that until you have transaction ability between Nigeria and Cameroon, Nigeria and Niger, Nigeria and Benin, you haven’t solved our problems.”
“A lot of Nigerian goods are being sold into most of West Africa, and people who used to carry cash across West Africa are now relying more on PAPSS. PAPSS is as good as cash – instant payments, where payment confirmations used to take two to three days before,” Ogbalu says. “We’re seeing that convenience is priced very highly by consumers, even over fees.”
And then this really interesting one: PAPSS is helping cement Nigeria’s religious influence across the continent, making it effortless for overseas worshippers to pay tithes and offerings to Nigerian churches.
This is not hard to believe. When I visited Zimbabwe in November 2024, the only faces on billboards along the airport road were the country’s president and a Nigerian Pentecostal pastor. At my hotel in Harare, a hotel worker stretched out his hand for a special handshake when he learnt I was from Nigeria – he turned out to be a huge fan of yet another Nigerian Pentecostal pastor.
Adoption drivers
You can transact on PAPSS through digital channels – internet banking, mobile banking, USSD – or you can step into a branch of a participating bank. “Digital channels now account for the bulk of our transactions, as against physical bank branches when we started,” Ogbalu says.
He added, “Once a commercial bank integrates PAPSS into their digital channels, we see a three-to-four-times increase overnight in their number of PAPSS transactions. Convenience is a key driver… Once you move anything to digital channels, adoption is higher. Consumers are intelligent; they don’t need any training to do PAPSS transactions.”
There’s a flexibility that PAPSS embodies: banks don’t even have to adopt PAPSS’ own designed user experience – “they can adapt it to their own regular UX.”
There’s also a correlation between national adoption rates and the vibrancy of a country’s startup ecosystem – the more the startup energy in a country, the likelier it is to embrace PAPSS.
System security and data integrity
Ogbalu says: “Data points are very important for us. PAPSS allows us to capture these, and we’ve improved on our data repository.”
A reassuring highlight about data privacy and security: “When transactions flow through our network, we do not keep Personally Identifiable Information (PII) or Know Your Customer (KYC) information on the people who’ve done the transactions – that data stays with the participating institutions, and the data is encrypted in transit and in processing and storage.”
As PAPSS has grown, so have the targets appearing on its back.
“The rate of attempts on our systems has more than doubled in the last six months, but we haven’t had a successful compromise. We continue to invest in improving security,” Ogbalu says, adding, “We have a holistic view of security – the chain is as strong as the weakest link; if you onboard an unwholesome partner, you’re compromising your security.”
PAPSS says it has strict vetting procedures for parties connecting to its infrastructure – all connectors must be certified by a Central Bank, and must also pass through Afreximbank’s centralised digital customer due diligence (CDD) and Know Your Customer (KYC) repository, known as MANSA.
Connectors and participants are all expected to abide by all the provisions of PAPSS’ bylaws. PAPSS has also set up a forum of heads of IT security from its member organisations, as a way of “extending the security perimeter” beyond Afreximbank. There is regular internal and third-party testing and review of the security architecture, including ethical hacking.
PAPSS is certified against ISO 27001 (information security), ISO 27701 (data privacy) and ISO 22301 (business continuity management). Its data is stored across multiple environments.
Additionally, there is an internal PAPSS incident management and reporting team that meets regularly. Ogbalu insists that PAPSS can compare with any payment system anywhere in the world, in every respect.
Data reporting
“We’ve given every regulator visibility on every transaction going into and out of their market. All the Central Banks have administrative access into our system; they don’t need to wait for us to submit any reports to them.”
He adds that PAPSS is working with its Governing Council to develop a framework that will guide public dissemination of its numbers (transaction volumes, etc.), and will then publish an overview of its first strategic plan phase, which comes to an end in 2026. (More on the strategic plans in Part 1, here.)
Central(ity of) Banks
There would be no PAPSS without the active participation and cooperation of the continent’s Central Banks:
- The PAPSS bylaws and its four governance organs were designed and created by Central Banks. (See Part 1 for details.)
- The PAPSS Governing Council, its highest decision-making organ, is made up of, at the moment, 15 central bank governors as voting members, complemented by representatives of Afreximbank, the AfDB, the AU and AfCFTA.
- Another of the governance organs, the Payment Systems Oversight Committee, which has direct oversight of operations, comprises directors of payments from the Governing Council’s central banks.
- Also, for a commercial bank to participate in PAPSS, it requires a letter of no objection from its supervising Central Bank. Ogbalu pointed out that national rates of adoption are closely tied to the level of Central Bank enthusiasm for PAPSS.
Crypto & blockchain
These, Ogbalu says, are “excellent technologies that will power the future of payments. Stablecoins are here to stay and can only grow. I must salute the Central Bank of Nigeria and the Securities and Exchange Commission for their very aggressive and proactive engagement on that front.”
Also: “Fiat currencies were designed to support physical trade, but content and value are increasingly becoming digital, and payment systems need to support this.”
As to how PAPSS intends to leverage blockchain technology, he says we should await further updates and announcements from them.
The challenges
There are challenges, no doubt – ranging from consumer awareness (”You can cook the best meal, but if people do not know this is available, there will be no fulfilment. Cooking is not enough; without the eating, there is no fulfilment”) to “invisible hands and influences” (”Remember us in your prayers; there are a lot of battles that need to be fought, and a lot of parties trying to undermine the work we’re doing”).
Government misconceptions are another big obstacle – the fear of some governments, for example, that PAPSS will “cannibalise” their existing domestic payment systems.
Ogbalu insists PAPSS is not here to compete or cannibalise – “our design principles have already taken care of those fears.”
Tolu Ogunlesi is an award-winning Nigerian journalist, writer and communications professional. He is a two-time CNN Multichoice African Journalism Award winner and former Special Assistant to President Muhammadu Buhari on Digital and New Media.